The Stockton counter is at 956 W Robinhood Dr, Stockton, CA 95207. San Jose is at 25 N 14th St #125. San Rafael is at 9 Vivian St. Call (209) 670-1556. Via Rapida Services is a registration service, not the DMV. A priced private-party sale is a different packet: title transfer when you buy a used car.
Which relatives qualify for the California use-tax exemption on a family car gift?
Revenue and Taxation Code §6285 exempts a vehicle from use tax when the person transferring it is the parent, grandparent, child, grandchild, or spouse of the person receiving it, or a brother or sister only when both are minors related by blood or adoption, and the person transferring it is not in the business of selling that type of vehicle. CDTFA Publication 52 and DMV handbook section 4.035 also cover a registered domestic partner and require form REG 256 to state the relationship. A stepparent, stepchild, aunt, uncle, or cousin is outside that statute unless a legal adoption creates one of the relationships the statute names.
The CDTFA vehicles exemption FAQ says the same list and adds that the exemption does not reach a stepparent or stepchild when no legal adoption creates the relationship, and that it does not apply between former spouses after a divorce decree. Handbook 4.035 cites Family Code §297.5 together with §6285 for the domestic-partner line. The statute text of §6285 itself names a spouse, not a domestic partner. Write the relationship on the REG 256. Do not write a cousin relationship into a parent line.
What does REG 256 do on a gift, and what else has to be signed?
DMV handbook section 4.035 treats a gift as not subject to use tax when the word gift is entered on the title in place of a purchase price and the person receiving the car completes a REG 256 Statement of Facts. The person giving the car signs the title. DMV handbook section 5.025, citing 49 CFR §580.5, requires an odometer disclosure when the transfer is on or after January 1, 2021 and the vehicle is less than 20 model years old. The handbook table lists a 2011 model as 15 model years old in calendar year 2026, which is still inside that window. The mileage is disclosed on the title or on REG 262, with original signatures in ink.
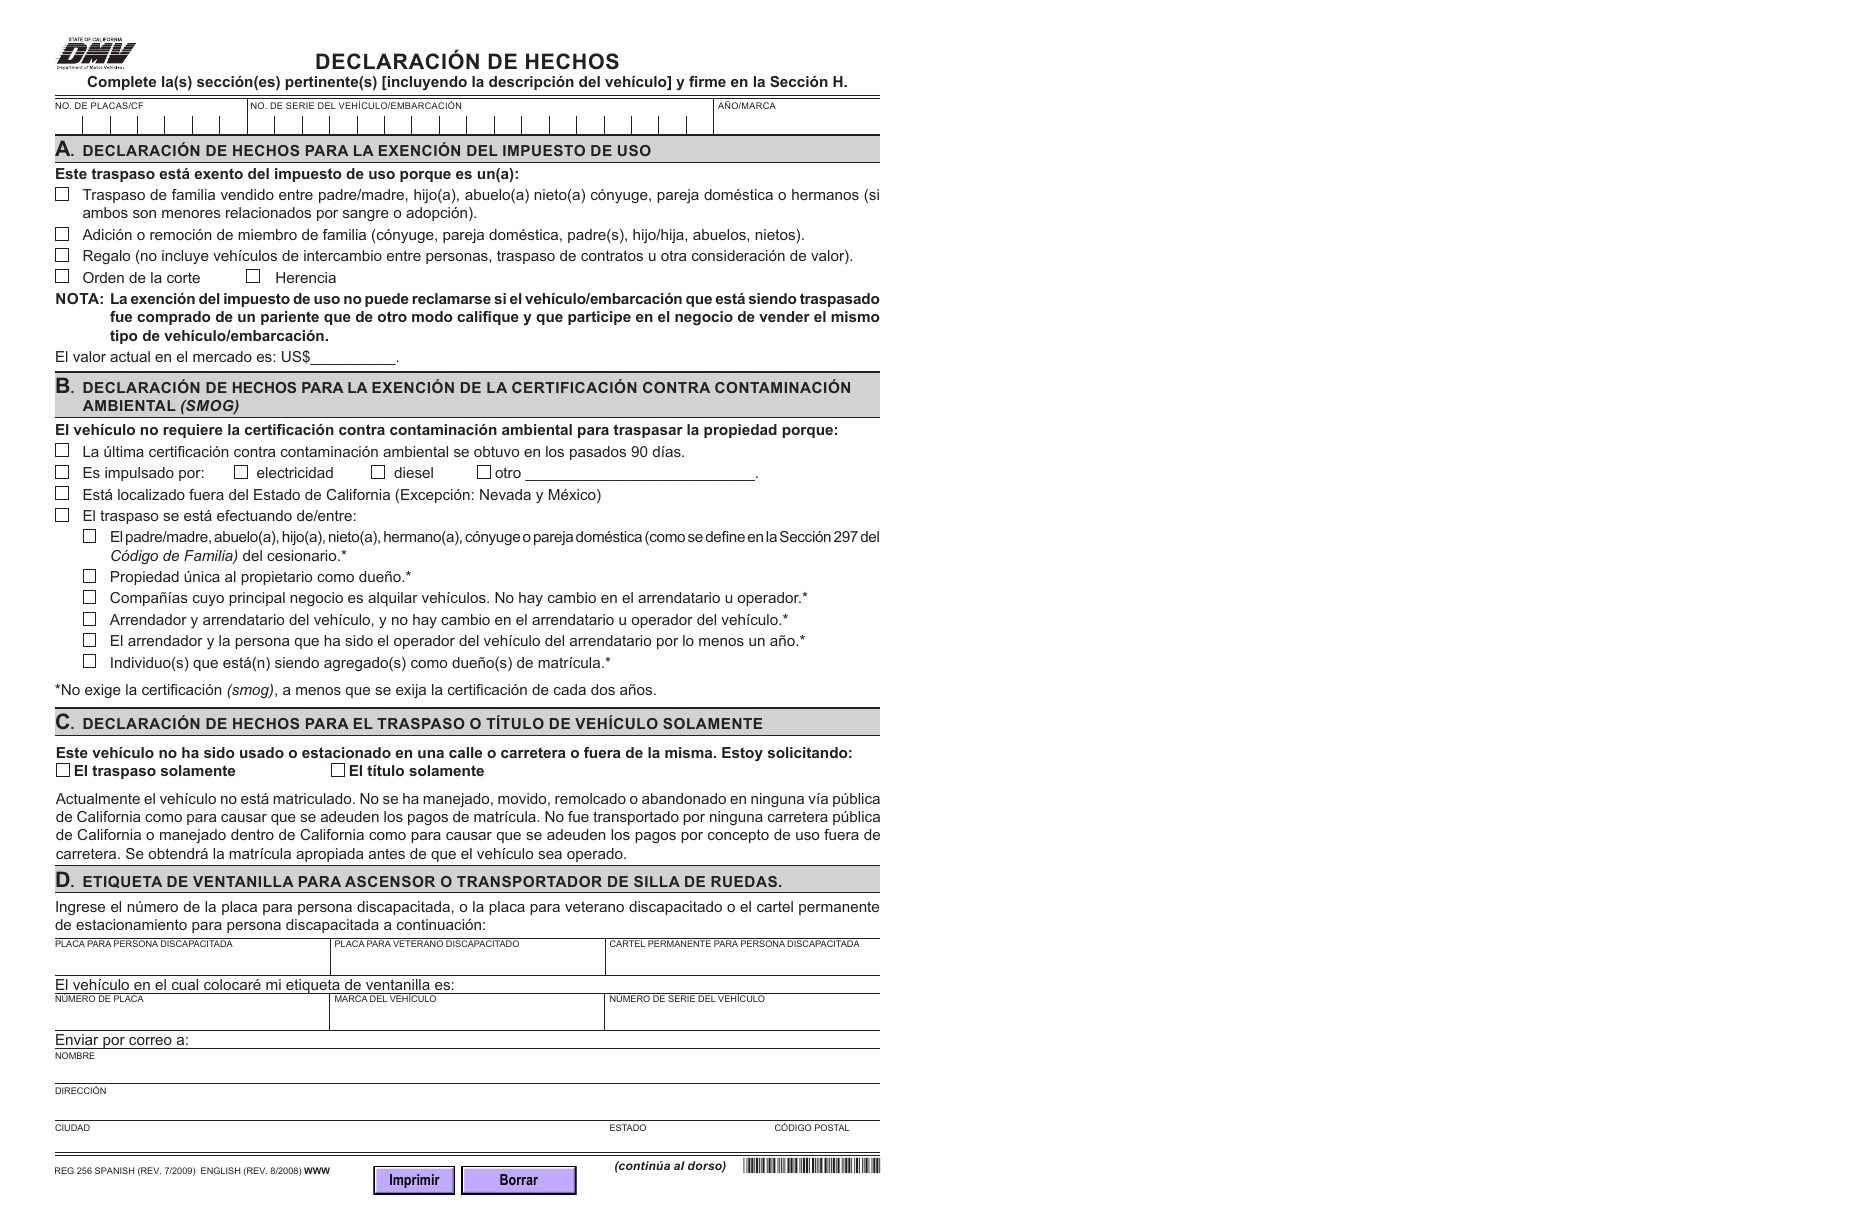
Section A of REG 256 is the use-tax statement, and it asks for current market value. Section B is the smog statement. Those two boxes do not list the same relatives. A family gift often needs both. Handbook 5.025 also says the disclosure needs an original signature in ink from the person giving the car and from the person receiving it. A power of attorney signature is not accepted for that disclosure. If the title cannot carry the mileage, both people sign the same REG 262.
Is a family gift exempt from the California smog inspection?
Vehicle Code §4000.1(d)(2) waives the transfer smog certificate when the transferor is the parent, grandparent, sibling, child, grandchild, or spouse of the transferee. A sibling of any age is on that smog list. The use-tax list in Revenue and Taxation Code §6285 is narrower: an adult brother or sister who sells the car for money is not in the use-tax exemption. Form REG 256 adds a domestic partner to the smog statement and cites Family Code §297. The statute text of §4000.1, amended in 2009, does not name a domestic partner. The same form says that box does not remove a biennial smog when one is due.
That split is the part families miss. An adult sibling can be inside the smog waiver and outside the family sale exemption at the same time. If the sibling transfer is a true gift, with no cash, trade, services, or loan takeover, the gift rule in Publication 52 is the use-tax path, not §6285. If the sibling transfer is a sale for a price, use tax follows the price unless both siblings are minors related by blood or adoption. The $8 path in §4000.1(d)(7) is separate: a vehicle four or fewer model years old pays that fee and, except for diesel, does not need a transfer smog certificate.
What transfer fee does the DMV charge, and what are the 10-day and 5-day clocks?
Vehicle Code §9255 sets a $15 fee to transfer title of an automobile or motorcycle, and DMV Appendix 1F lists Transfer (VC §9255) at $15. That chart was checked on 4 October 2026. Vehicle Code §5902 gives the new owner 10 days after receiving the endorsed title to forward it to the department with the transfer fee. Vehicle Code §5900 gives the person who gave the car five calendar days to notify the department of the transfer. That notice is the Notice of Transfer and Release of Liability, and the paper form is REG 138. The DMV says filing the notice does not transfer ownership by itself.
The two clocks belong to different people. The person who received the endorsed title has the 10-day application. The person who gave the car has the five-day notice, online or on paper REG 138, with the new owner's name and address, the plate, the mileage, and the date. Signing the title does not erase that five-day duty. Vehicle Code §5602 is a liability rule for the former owner. It is not a substitute for the new owner's transfer application under §5902. The $15 figure is the state transfer fee. A registration service states its own service charge before the papers go in. That charge is separate, and it is quoted before filing. County use tax, when a transfer is not exempt, is computed by the DMV from the price or the market value. This page does not print a county rate.
What changes when the gift is to a friend or a relative outside the statute?
A true gift to a friend can still be outside use tax. CDTFA Publication 52 says California use tax is not due on a vehicle received as a gift, unless the recipient paid cash, traded property, performed services, or took over a loan, or an employer gave the vehicle as compensation. Publication 52's example is a friend who gives a car and the recipient agrees to take over the loan: use tax is computed on the remaining loan balance and any other consideration. DMV handbook 4.035 still wants the word gift on the title and a completed REG 256. The smog waiver in Vehicle Code §4000.1(d)(2) does not cover a friend, cousin, aunt, or uncle. A vehicle four or fewer model years old can instead fall under §4000.1(d)(7), which charges an $8 fee and, except for diesel, does not require a transfer smog certificate.
Handbook 4.035 also says the gift treatment does not apply to a transfer of contract. If a balance stays with the lender and the new owner picks up the payments, Publication 52 treats that balance as consideration. Write the facts on the REG 256. Do not write gift over a loan takeover and hope the counter misses it. For a friend, plan on a smog certificate unless another paragraph of §4000.1 applies, such as a certificate already inside its 90-day validity or a vehicle four or fewer model years old.
What proof of insurance does the new owner need before driving?
Vehicle Code §16020 requires every driver and every owner to be able to establish financial responsibility and to carry the evidence in the vehicle before it is driven. For a policy or bond issued or renewed on or after January 1, 2025, Vehicle Code §16056(a)(2) sets the floor at $30,000 for bodily injury or death of one person, $60,000 for bodily injury or death of two or more persons, and $15,000 for property damage. Vehicle Code §5602 says a person who made a bona fide transfer and delivered the vehicle is not, under this code, liable for later parking, abandoning, or operation if that person also endorsed and delivered the title or delivered or mailed the §5900 notice. The notice is not a liability policy for the new owner.
Evidence under §16020 can be the insurer's form or a binder under Insurance Code §382 or §382.5. Put that evidence in the car before it moves on a public road. The policy has to meet §16056 for a policy issued or renewed on or after 1 January 2025. We can look for a liability policy in the new owner's name from the same three counters. A carrier decides whether to offer it. We do not promise an approval. If a later lapse suspends the registration, read registration suspended for an insurance lapse. Statewide liability coverage is on California car insurance.
Sources
- Revenue and Taxation Code §6285 (family vehicle exemption; also on the CDTFA law guide). Checked 4 October 2026.
- CDTFA Publication 52, Vehicles and Vessels: Use Tax (gift rule, family purchase, loan-takeover example, domestic partner). Checked 4 October 2026.
- CDTFA exemptions FAQ for vehicles, vessels, and aircraft (step-relations and former spouses). Checked 4 October 2026.
- DMV handbook 4.035, Transactions Not Subject to Use Tax (gift wording, REG 256, family and domestic-partner transfers). Checked 4 October 2026.
- DMV REG 256, Statement of Facts (use-tax section, smog section, market-value line, biennial-smog note). Checked 4 October 2026.
- Vehicle Code §4000.1 (family smog waiver in (d)(2); $8 fee for a vehicle four or fewer model years old in (d)(7)). Checked 4 October 2026.
- DMV handbook 5.025 (odometer disclosure, 49 CFR §580.5, model-year table). Checked 4 October 2026.
- Vehicle Code §9255 and DMV Appendix 1F (transfer fee $15). Chart checked 4 October 2026.
- Vehicle Code §5902 (10 days) and §5900 (five calendar days). Checked 4 October 2026.
- DMV Notice of Transfer and Release of Liability (REG 138; notice is not the transfer). Checked 4 October 2026.
- Vehicle Code §5602, §16020, and §16056. Checked 4 October 2026.
Reviewed by Santo Militello, California-licensed Property & Casualty agent (CA License #1737723) and owner of Via Rapida Services. Insurance City Agency, LLC · CA License #6003045. Our licensed team brings more than 70 years of combined insurance experience. Call (209) 670-1556. Last reviewed 2026-10-04.